A new paper (in Portuguese) by Carlos Medeiros and Esther Majerowicz analyzes the economic relationship between China and Brazil using the center–periphery framework developed by Raúl Prebisch. It argues that, in the 21st century, this relationship reflects a dual process: China’s rise as a new global economic “center” and Brazil’s passive adaptation as a peripheral economy, reinforcing asymmetric development patterns.
A key claim is that China has become central not just because of its size, but because it is now a major source of industrial production and technological innovation, influencing global demand, trade patterns, and commodity prices. Its growth has reshaped the world economy, especially by increasing demand for raw materials and lowering prices of manufactured goods. For Brazil, this has led to a reprimarization of exports. The country increasingly exports commodities (soy, iron ore, oil) to China while importing manufactured goods. This pattern strengthens traditional center–periphery dynamics, despite being framed politically as South–South cooperation. This suggests similar problems as identified by myself and Esteban Pérez in a paper discussing the development strategies in Latin America. The main difference is that in the last decade and a half, the central position of China is more clear, even if the typical notion that American hegemony is over has been exaggerated in American liberal circles.
The authors identify two possible development paths. The dominant one is a business as usual strategy, aligned with Chinese demand and Brazilian agribusiness and mining interests, which deepens dependency. The alternative is a developmental strategy based on diversification, industrial upgrading, and technological cooperation, but this path seems currently unlikely. They also emphasize that Chinese investment in Brazil is concentrated in extractive industries and infrastructure, reinforcing the existing specialization pattern, although there are some emerging opportunities in sectors like renewable energy and digital technologies.
Finally, the paper argues that shifting toward a more balanced relationship would require active state planning, political will, and supportive social coalitions in Brazil. Without these, the current asymmetrical structure is likely to persist or deepen.
Saturday, May 2, 2026
The New Center-Periphery Relations
Wednesday, March 11, 2026
Development by invitation: a short digression on the concept
The concept of development by invitation, as far as I know, and most of my knowledge comes from Esteban Pérez's paper in a book we co-edited long ago, originates with Arthur Lewis and refers to a development strategy in which small developing economies attract foreign capital to initiate industrialization. For Lewis, the problem of many small developing economies, particularly in the Caribbean, was that they lacked several key elements required for industrialization, namely: domestic capital, entrepreneurial skills and large domestic markets. Because of these constraints, industrialization could not easily emerge through domestic investment alone. Lewis therefore proposed industrialization by invitation, meaning that governments should invite foreign firms to establish manufacturing activities in the country.
Immanuel Wallerstein refers to a path of development in which a peripheral country advances economically because the multinational corporations from central countries actively expand into the world economy. This development occurred not through autonomous national transformation, but through external investment resulting from political and economic cooperation with central countries. For Wallerstein, the concept referred to a structural process within the capitalist world-system. In his framework, central countries allowed limited industrialization in some peripheral areas as multinational firms relocated production. That was, in fact, to some extent the phenomenon in a good part of the Latin American periphery, In other words, development by invitation was not a development policy, but a mechanism of global capitalism that reorganized production.
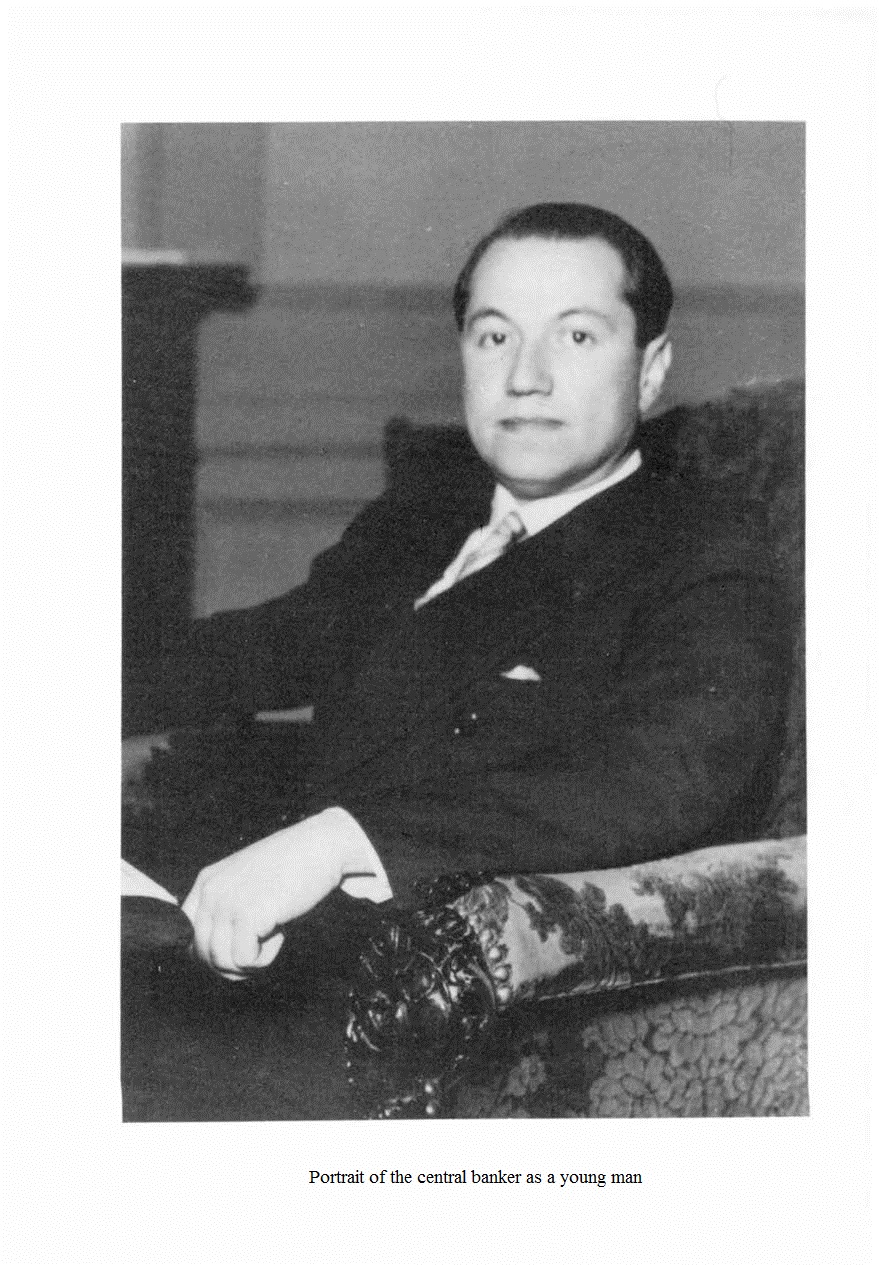
In the work of Carlos Medeiros (published with Franklin Serrano; he is pictured above), the notion of development by invitation refers to a historical process in which peripheral or late-industrializing countries accelerate their development because the leading powers of the international system actively support or tolerate their industrialization for geopolitical reasons. The concept is embedded in their analysis of international monetary regimes and growth dynamics. Growth is demand-led, and based on the supermultiplier, if that wasn't clear.
For Medeiros, the starting point is that capitalism naturally generates divergence between countries due to structural asymmetries in military power, technological capabilities, and monetary hegemony. All three are interrelated. Because of these asymmetries, most peripheral countries face a balance-of-payments constraint that limits growth. However, in certain historical periods, some countries can overcome these constraints when the dominant power facilitates their development.
For Medeiros, development is not simply the relocation of production associated to multinational or transnational firms, be that as a policy strategy or an endogenous process of integration within the capitalist system. It involves state-led industrialization and strategic geopolitical support from the hegemonic power. Hence, development by invitation can produce successful industrial catch-up, not merely integration into the world economy.
Note that Esteban's discussion implicitly highlights a critique of the early concept from a structuralist perspective. Even though Lewis viewed the strategy as a path to development, in practice it often led to enclave industrialization and persistent dependence on multinational firms. The outcome sometimes resembled the type of dependent integration emphasized by Wallerstein. In a sense, Medeiros version is a further critique, suggesting that the interaction of political coalitions, behind the developmental state, and the geopolitical context matter.
Note that one might be correctly skeptical of the notion that a country develops simply because the hegemonic power invites it to do so. Even acknowledging that favorable geopolitical contexts existed, such as those of Japan, South Korea, or several European countries in the postwar period, one might argue that development was ultimately the result of internal strategies, that is, strong states pursuing active industrial policies of technological catch up. In this view, the invitation may have constituted a favorable external framework, but it was never the decisive factor.
However, this critique appears to address a somewhat simplified interpretation of Medeiros’ concept. In his framework, development by invitation was never presented as a purely external process or as a microeconomic explanation based on private decisions. The concept was formulated in macroeconomic and geopolitical terms, placing emphasis precisely on the role of the state. The question was not whether Japan or Korea developed simply because the United States invited them, but rather why certain developmental states were able to industrialize so rapidly through manufactured exports. The answer highlights that these states benefited from exceptional external conditions. First, the unilateral opening of the US market, financial transfers, very often facilitated technological transfers, beyond tolerance toward aggressive industrial policies, and strategic support within the context of the Cold War. This was not diplomatic magic, but rather a combination of an internal developmental state and a relaxation of the external constraint facilitated by American hegemony.
In other words, Medeiros’ concept does not attempt to explain development exclusively through external factors, but rather to illuminate why certain developmental states faced fewer external constraints, had greater access to financing, and enjoyed broader access to strategic markets than others. This allowed for a particular mix of export promotion and import substitution and helps explain why several Asian countries not only avoided the lost decade that followed the debt crisis of the 1980s, but also managed to accelerate their process of industrialization as a good part of the center, and other peripheral regions deindustrialized.
If the discussion is brought to the current Argentine case (I wrote a short note on this in Spanish), the most important point may not be to deny the relevance of the concept but to recognize that Argentina today lacks a developmental state capable of taking advantage of any potential invitation. If the government dismantles industrial, technological, and financial policy instruments, then whether a country is invited or not becomes almost irrelevant. The issue is not whether Washington extends a diplomatic invitation, but whether there exists a national strategy capable of transforming a favorable geopolitical context into productive accumulation.
Ultimately, the debate should not revolve around whether development arrives mechanically by invitation, but rather around the interaction between internal state strategy and external conditions. Development has never been automatic or purely external, but neither has it been independent of the geopolitical order and the decisions of the hegemonic power.
Friday, November 21, 2025
Chapter on the history of monetary policy for the Elgar Companion to the Economies of Latin America and the Caribbean
My paper with Esteban Pérez has been published and is available now here. From the abstract of our chapter:
Monetary policy in Latin America has evolved in five different phases. The first one is characterized by the establishment of the first central banks adhering to a gold standard. The second phase is marked by the abandonment of the gold standard and the adoption of discretionary over rules based monetary policy. The third phase consists in the generalized adoption of developmental and inward industrialization goals by central banks. The fourth phase places price stability as the key overriding objective of monetary policy. The last phase focusses on the adoption of inflation targeting within an open economy context. The evolution of monetary policy in the region is closely related to the developments in the external sector and with the needs associated with the integration with the global economy. The chapter will emphasize the relative difficulties of insulating the region from external monetary and financial volatility and the limitations faced by monetary institutions to promote economic development with price stability.
An earlier version can be read here.
Thursday, May 8, 2025
More on MMT in the Tropics: or Can exchange rate instability, and zero interest rates, guarantee prosperity in the periphery?
Back in the 1990s (from late 1996 to early 1999 to be precise), I worked for Wynne Godley at the Levy Institute. Minsky, that I saw in Brazil once, had just passed away. Randy Wray was at the Levy at an office not far from Wynne's, where we worked on his model. I was, also, in Ed Nell's study group (Matt Forstater was a frequent visitor), that met regularly and discussed functional finance. In fact, one of the few topics that I was first exposed at the New School, rather than at my alma mater in Brazil.
Ed organized a conference on functional finance in 1997 (if memory doesn't fail me), then published as a book (see here), which in many ways was the beginning of what later would be called Modern Money Theory (note that at the core was Abba Lerner's functional finance). At dinner (at the Orozco Room) I sat at a table with Musgrave, Duesenberry, and, for a brief moment, Eisner, that had to leave early.* I think that was the first time I met Mosler.** Randy's MMT book came next year, in 1998 (I should note that I paid less attention to that book than his previous one, based on his PhD dissertation under Minsky, since I was at the time writing my own dissertation under Wynne and Lance Taylor, both pictured above on the day of my defense).
I start this, just to explain what should be obvious, that functional finance, endogenous money, and a preoccupation with full employment not only are part of my concerns, but that I learned, at least in part, some of these ideas more or less at the same time that they were being discussed and the MMT school was being formed. Mind you the notion of effective demand, and the perils of the external constraint, were things I already knew, but some of the issues with value theory and its importance for policy I also learned with Ed, and John Eatwell, at the New School. Further, on a personal note, I should clarify that while I worked for Wynne, who at the time was concerned with the growing external imbalances of the US, and the consequences for the international position of the dollar, I tended, on this topic to be closer to Randy's views, since it was clear for any one that came from the Federal University in Rio, and who had been influenced by Maria da Conceição Tavares, that the dollar was under no danger, and the US by definition didn't have an external constraint.
All of this to say, again, that in general, I do agree with the notion that autonomous spending determines income, and taxes being charged out of income, are the result of spending, and, as a result, the limit to fiscal policy is essentially political in nature. That is something that MMT has been instrumental in popularizing in the United States, and whenever I can, I do help on that (see my podcast with Stephanie Kelton, who was at Levy when I worked there, and started her PhD at the New School slightly after I did). She was here at Bucknell to discuss the documentary Finding the Money.
This introduction, longish and winding, is to explain why it is somewhat weird to discuss this paper by Arturo Huerta, who I have met in Mexico, but do not know very well. This is difficult because it is a misrepresentation of the differences I do have with MMT. His paper is supposedly a rebuttal to some arguments that we have made with Esteban Pérez on Modern Money Theory (MMT). The paper is a mix of name calling (essentially that we are conventional or orthodox, read, neoclassical, and that we are neoliberals or aligned with them) and a series of arguments in defense of flexible exchange rate regimes as a solution for unemployment problems in peripheral countries. The title, "Exchange-Rate Stability Causes Deterioration of the Productive Sphere and Destabilizes Developing Economies," seems to go even further and advocate for exchange rate instability. For Minsky financial stability was destabilizing, for some MMT authors exchange rate stability causes underdevelopment and is also destabilizing.
In fact, this seems to be more a response to the critique, mine more than Esteban's, to Warren Mosler's proposal for Argentina (see below),* which would definitively cause more exchange rate instability, inflation and a huge recession, than to our original discussion of MMT in developing countries. In fact, Huerta does not cite that paper, but our response to a poorly developed and somewhat misleading paper by Agustin Mario, that I discussed here, who said without any evidence that we defended supply side views of economic growth.
Mosler's plan consists of free float (which he says retains foreign reserves), a zero (yep, that is zero) interest rate irrespective of the rate of interest in the United States, and a Job Guarantee (JG) program. The rest is less relevant, at least for our purposes. I also assume some expansionary fiscal policy on top would be necessary for the JG.
Huerta's main point is that a flexible exchange rates would free the country to spend in domestic currency, very much like Mosler suggests, without loss of reserves, which developing should not be concerned with in the first place. He essentially argues along Wray's lines according to which: "a government does not need to fear that it will run out of foreign currency reserves (or gold reserves) for the simple reason that it does not convert its domestic currency to foreign currency at a fixed exchange rate" (from Wray's Modern money theory: a primer on macroeconomics for sovereign monetary: p. 161. It is still exactly like that in the 2024 edition).
The notion is that: "a floating currency provides more policy space – the ability to use domestic fiscal and monetary policy to achieve policy goals. By contrast, a fixed exchange rate reduces policy space" (Ibid.). Of course, a fixed exchange rate is not necessarily the same that a stable one, and the notion that allowing big devaluations is counter-productive. MMTeers may say, as I'm sure they will, we do not defend big devaluations. Maybe not explicitly, but if you keep low (zero interest rates), and do not intervene in the exchange rate market, that is, unavoidably, the consequence. Doing that will not retain reserves, and central banks should be concerned about reserves. Btw, Milei was able to reduce inflation drastically because he did intervene both in the official and the parallel exchange rate markets (and the loan from the IMF is essentially about recomposing reserves; more on that in another post).
Then comes the question of why you should be concerned with reserves, and here Huerta's position is somewhat puzzling, particularly for someone coming from a developing country. I quote here, he says: "Vernengo and Pérez (2021) do not consider that purchases of imported goods are paid for in the importing nation’s currency, accepted by the exporters so that they can make investments, acquire financial assets, and make purchases in that nation." He suggests that they would accept pesos. In this view, a country that is an oil importer, that cannot function without energy, can import oil in domestic currency. Good luck with that!
But even if we leave the realm of Latin American magical realism, an the notion that developing countries can import in its own currency the basic capital and intermediary goods that they need to maintain normal levels of activity, his view is full of problems. He accepts very conventional views about the exchange rate (while claiming that I do have orthodox views, which I never did, on fiscal austerity; on that, note that The Guardian quotes me twice, here and here, as being against austerity when many heterodox economists, some even arguably MMTeers, I might add, have been for austerity in Argentina, saying that the mistake of the Kirchners was their fiscal excesses).
His main argument is that a "flexible exchange rates are important ... for increasing the competitiveness of national productivity and reducing pressures upon the external sector." He repeats it, saying that: "A flexible exchange rate improves competitiveness and promotes economic growth, thereby reducing the current account deficit." In other words, the flexible exchange rate does solve the external problem (Randy is always more careful about that, and I have not seen that argument in his work).
He says that: "the reason for MMT’s advocacy of flexible exchange rates is so that the exchange rates may adjust to differences between domestic prices and those of the principal trading partners. By allowing those adjustments, a nation can avoid the relative-price distortions that would affect national production." *** He notes, as I suggested above, that they are not for depreciation per se (yeah, but with a zero interest rate...), but that: "the predominant exchange rate stability (achieved by maintaining high interest rates, in order to promote capital inflow) has led to exchange rate appreciation, which is detrimental to the competitiveness of national production." In this, as we noted in our original paper with Esteban, they are very similar to Bresser-Pereira's New Developmentalism. In the concern with a competitive exchange rate, but with a tolerance, if not a promotion of exchange rate instability, which is inevitable with very low interest rates.
There are many other issues, which again reveal actual use of marginalist thinking, for example, he says: "In saying that low interest rates generate inflation, these authors presuppose that low rates increase demand, and that the economy is in full employment. However, Vernengo and Pérez do not consider the fact that low interest rates favor the growth of investment, production, and productivity." First of all, that misrepresents our views. Low interest rates, leading to a negative interest rate differential (when the local rate is lower than the US rate adjusted for risk) leads to depreciation, and higher costs of imported goods, and inflation even if the economy is below full employment (I published the model in a book edited by, wait for it ... Forstater and Wray). Inflation comes from distributive conflict, and a depreciation, by affecting the costs of production and reducing real wages, stokes inflation. Second of all, his point is that lower interest rates lead to higher investment, which is a marginalist view that associates the intensity of the use of capital with its remuneration, a problem Huerta and many Post Keynesians share with Keynes.**** I follow Sraffians and prefer to abandon marginalist principles.
Huerta puts emphasis on the role of investment as central for growth, and in the need of very low interest rates for that, irrespective of their effect on exchange rate instability. He actually says several times that exchange rate stability is a problem, and argues that: "economies that give priority to exchange-rate stability cannot employ flexible monetary and fiscal policies to stimulate growth." On this, my views are closer to Ricardo Summa, that notes that investment is not so unstable, and follows the accelerator, and that autonomous demand (the non capacity generating part of it) is central for explaining growth.
So one needs a managed exchange rate, to avoid the inflationary pressures, and one needs to be concerned with reserves to be able to avoid the perils of not being able to import essential goods, that would cause bottlenecks an impede growth. But Huerta knows that, as a friend noticed (see below).
As he says in his tweets, what would Mexico do if it runs out of dollars to buy corn? Why not use pesos instead then? I mean, I get that Vernengo did not consider that, but he is an orthodox economist, isn't he?
In other words, sometimes, and certainly not always, developing countries cannot pursue expansionist fiscal policies because they do NOT HAVE DOLLARS (there is a reason every country, even China, accumulated humongous reserves of dollars after 2008-9). In order to be able to do it, sometimes, higher rates are needed in the periphery (not so much in the US). Then expansionary fiscal policy can be pursued even with higher interest rates, and the economy would be able to grow (as would investment that would respond, not to the higher interest, but to higher levels of demand). Exchange rate competitiveness is not central for growth, and Latin America did its State-led, import substitution industrialization (that Huerta cites all the time) during Bretton Woods with a stable nominal exchange rate (Mexico had a fixed rate from 1954 to 1976; they call it stabilizing development). It was a period of high growth, and relatively stable and appreciated exchange rate.
* I did co-edit a book, that had what I think was the last paper written by Eisner and can be seen as a follow up to that conference (ours what out of a few sessions we co-organized at the Easterns in DC in 2004, on functional finance issues.
** Mosler was in Argentina and presented this in several venues, including, at the University of Moreno, where someone questioned the idea that flexible rates with zero interested was feasible, and correctly noted that it would be inflationary and contractionary. He proceeded to ask if the person worked with me, as the story was related to me. As if my position on this is somewhat unique and someone that suggests that it doesn't make sense is my disciple.
*** Note that for Huerta exchange rates change relative prices and allow to fix distortions, in typical marginalist fashion. The emphasis is not on the effects on distribution and through that on quantities, as in structuralist views.
**** This blog is known for emphasizing the Sraffian critique of the marginalist theory of investment (very old post on that).
Sunday, May 19, 2024
Esteban Pérez Caldentey on the Ideas of Raúl Prebisch
Esteban Pérez's talk at the University of Chile, about Raúl Prebisch, about whom we have written several papers. This is in Spanish.
Thursday, February 1, 2024
Dollar Hegemony and Argentina
First part of a two part interview with Anita Fuentes at Security in Context. The discussion on Argentina and Milei is in the next part. I'll post it as soon as it is up.
Tuesday, September 19, 2023
Dollar Hegemony, coming soon
Friday, February 5, 2021
The New IMF and the Covid Crisis
Saturday, October 31, 2020
Esteban Pérez on John Maynard Keynes
One of my favorite economists, and John Maynard Keynes too. Don't miss this lecture, in Spanish of course, on one of the central economists of the 20th century and its relevance for the periphery, particularly during the current pandemic. I'll post links to the Zoom and Facebook stream soon.
Monday, December 30, 2019
Raúl Prebisch as a Central Banker and Money Doctor
Here we edited with Esteban Pérez and Miguel Torres some unpublished manuscripts from Prebisch related to the Federal Reserve missions, led by Robert Triffin, to the Dominican Republic and Paraguay, in which he emphasizes the need of capital controls in peripheral countries that did NOT have the key hegemonic currency. There is also a discussion of Keynes and White's plans for Bretton Woods, which were partially published before. In Spanish. Happy New Year!
Monday, September 16, 2019
New Book on Roy Harrod
Esteban Pérez Caldentey has just published a new book on Roy Harrod for the collection edited by Anthony Thirlwall. From the description:
This landmark book describes and analyzes the original contributions Sir Roy Harrod made to fields including microeconomics, macroeconomics, international trade and finance, growth theory, trade cycle analysis and economic methodology. Harrod’s prolific writings reflect an astounding and unique intellectual capacity, and a wide range of interests. He became Keynes´ biographer and wrote a volume on inductive logic. At the policy level, Harrod played a central role in the formulation of the Keynes´ Clearing Union plan for international monetary reform. He also actively participated in British politics and government and gained recognition as an expert in the field of international economics. Yet, until now, Harrod has remained an underrated economist, commonly misunderstood and misrepresented. This is the first major intellectual biography of Harrod to be published.For more and to buy it go here.
Monday, January 7, 2019
Raúl Prebish’s Unpublished Manuscripts on the Buenos Aires Lectures on Economic Dynamics
By Esteban Pérez Caldentey
Raúl Prebish’s Unpublished Manuscripts on the Buenos Aires Lectures on Economic Dynamics edited by Esteban Pérez Caldentey (ECLAC) and Matías Vernengo (Bucknell University), have been published in the ECLAC Review, August 2018
Raúl Prebisch (1901–1986), the Second Executive Secretary of the Economic Commission for Latin America and the Caribbean (ECLAC) which he joined in 1949 is mostly known for his long-run analysis and diagnostic of the development problem of Latin America, which he fully stated in “The economic development of Latin America and some of its principal problems” (1950), also known as Prebisch’s “Manifesto”.
However, prior to joining ECLAC Prebisch also devoted a great part of his time and career the analysis of business cycles in theory and in practice (he was the first Director General of the central bank of Argentina created in 1935 and Prebisch himself drafted the project for the bank). On the basis of his cycle analysis he began to develop a theory of dynamics which sought to introduce two elements that, according to Prebisch, were missing from the Classical and Keynesian analyses, time and space.
Prebisch argued that capitalist economies evolved and developed in growth cycles. From 1920 to 1944 his analyses of capitalism centered on Argentina and on the characteristics of its business cycle. He attributed the phases of the Argentinean cycle to external causes determined to a large extent by the policy and economic performance in developed countries (Great Britain and the United States).
Sunday, November 11, 2018
Heterodox Central Banking in the Periphery
Traditionally, monetary policy in Latin America followed the recommendations of the missions of the monetary “doctors” who defended an independent central bank and a pro-cyclical monetary policy, adhering to the automatic adjustment of the gold standard. A key function of central banks was to support fiscal stability. The effects of the Great Depression and its aftermath in the periphery countries questioned these recommendations and gave way to a shift in monetary policy. An illustrative example is provided by the creation of the Central Bank of the Argentina Republic (BCRA) under the auspices of Raúl Prebisch, and the technical assistance missions of the United States Federal Reserve to several Latin American countries some of which were led by Robert Triffin. Prebisch actively participated in mission to Paraguay and the Dominican Republic bringing the experience he had acquired as director of the BCRA and the tools devised to adapt monetary policy to a changing external context and circumstances. The use of the discount window and exchange controls, among other instruments, was seen in this new view as necessary to pursue counter-cyclical policies and to provide support for industrialization and full employment in the periphery.Read rest here.
Tuesday, June 5, 2018
Financialization in Latin America
New book edited by Martín Abeles, Esteban Pérez Caldentey and Sebastían Valdecantos. From the description:
The chapters in the book analyze the logic and effects of financialization in developing economies, peripheral financialization so to speak, in particular in Latin America. The first chapters look at the topic from a historical and conceptual angles, and then the latter chapters concentrate on specific manifestations like the influence of financialization on productive investment, spending on Research and Development (R&D), the characteristics of Foreign Direct Investment (FDI), monetary policy management, and the composition of foreign debt. The variety of approaches utilized in this volume reflect ECLAC's historical preoccupation of analyzing the condition that would make possible a macroeconomics at the service of economic development.
Wednesday, May 23, 2018
Integration, spurious convergence, and financial fragility: a post-Keynesian interpretation of the Spanish crisis
Paper co-authored with Esteban Pérez that was a Levy Institute working paper is published. From the abstract:
The Spanish crisis is generally portrayed as resulting from excessive spending
by households associated to a housing bubble and/or an excessive welfare spending beyond
the economic possibilities of the country. We put forward a different hypothesis. We argue
that the Spanish crisis resulted, in the main, from a widening deficit position in the non-
financial corporate sector and a declining trend in profitability under a regime of financial
liberalization and loose and unregulated lending practices.
Full paper available here.
Saturday, May 5, 2018
Corporate Debt in Latin America and its Macroeconomic Implications
This paper provides an empirical analysis of nonfinancial corporate debt in six large Latin American countries (Argentina, Brazil, Chile, Colombia, Mexico, and Peru), distinguishing between bond-issuing and non-bond-issuing firms, and assessing the debt’s macroeconomic implications. The paper uses a sample of 2,241 firms listed on the stock markets of their respective countries, comprising 34 sectors of economic activity for the period 2009–16. On the basis of liquidity, leverage, and profitability indicators, it shows that bond-issuing firms are in a worse financial position relative to non-bond-issuing firms. Using Minsky’s hedge/speculative/Ponzi taxonomy for financial fragility, we argue that there is a larger share of firms that are in a speculative or Ponzi position relative to the hedge category. Also, the share of hedge bond-issuing firms declines over time. Finally, the paper presents the results of estimating a nonlinear threshold econometric model, which demonstrates that beyond a leverage threshold, firms’ investment contracts while they increase their liquidity positions. This has important macroeconomic implications, since the listed and, in particular, bond-issuing firms (which tend to operate under high leverage levels) represent a significant share of assets and investment. This finding could account, in part, for the retrenchment in investment that the sample of countries included in the paper have experienced in the period under study and highlights the need to incorporate the international bond market in analyses of monetary transmission mechanisms.Read full paper here.
Thursday, November 2, 2017
Monitoring the evolution of Latin American economies using a flow-of-funds framework
Saturday, August 5, 2017
"Wages, prices, and employment in a Keynesian long-run" by Marglin
The central question this paper addresses is the same one I explored in my joint work with Amit Bhaduri 25 years ago: under what circumstances are high wages good for employment? I extend our 1990 argument in three directions. First, instead of mark-up pricing, I model labor and product markets separately. The labor supply to the capitalist sector of the economy is assumed à la Lewis to be unlimited. Consequently the wage cannot be determined endogenously but is fixed by an extended notion of subsistence based on Smith, Ricardo, and Marx. For tractability the product market is assumed to be perfectly competitive. The second innovation is to show how disequilibrium adjustment resolves the overdetermination inherent in the model. There are three equations – aggregate demand, goods supply, and labor supply – but two unknowns – the labor–capital ratio and the real price (the inverse of the real wage). Consequently equilibrium does not even exist until we define the adjustment process. The third innovation is to distinguish capital deepening from capital widening. This is important because, ceteris paribus, wage-led growth is more likely to stimulate the economy the greater the fraction of investment devoted to capital deepening. A final section of the paper shows that US data on employment and inflation since the 1950s are consistent with the theory developed in this paper.Marglin's paper is open, and so is Bhaduri's. Full issue here.
Thursday, June 29, 2017
Prebisch and Central Banking
Wednesday, March 8, 2017
Quantitative Easing (QE), changes in global liquidity and financial instability
This paper argues that QE led to significant changes in the global financial system, which, are not conducive to greater financial stability. Through a policy of reserve accumulation, QE disconnected base money from the money supply and deposits from loans. Jointly with the deleveraging process of global banks, QE contributed to restrain the supply of bank credit growth throughout the world. Also global banks continued to expand their trading on the basis of opaque instruments such as derivatives. Moreover, by altering the relative profitability of investing in different assets, QE exerted a positive effect on the performance of the international bond market. This not only spilled into emerging market economies expanding the debt of both the financial sector and the non-financial corporate sector but also has reinforced the role of the asset management industry in financial markets. Due to its concentration and interconnectedness, illiquidity, and pro-cyclicality the asset management industry poses important risks to financial stability.Read full paper here.